
CelcomDigi Berhad has announced its second quarter results for the Financial Year 2026 (FY2026), reporting year-on-year service revenue growth supported by its Postpaid, Home and Fibre, and Enterprise segments, alongside continued progress in its Operational Excellence (OE) program.
CelcomDigi Service Revenue Grows In Q2 FY2026
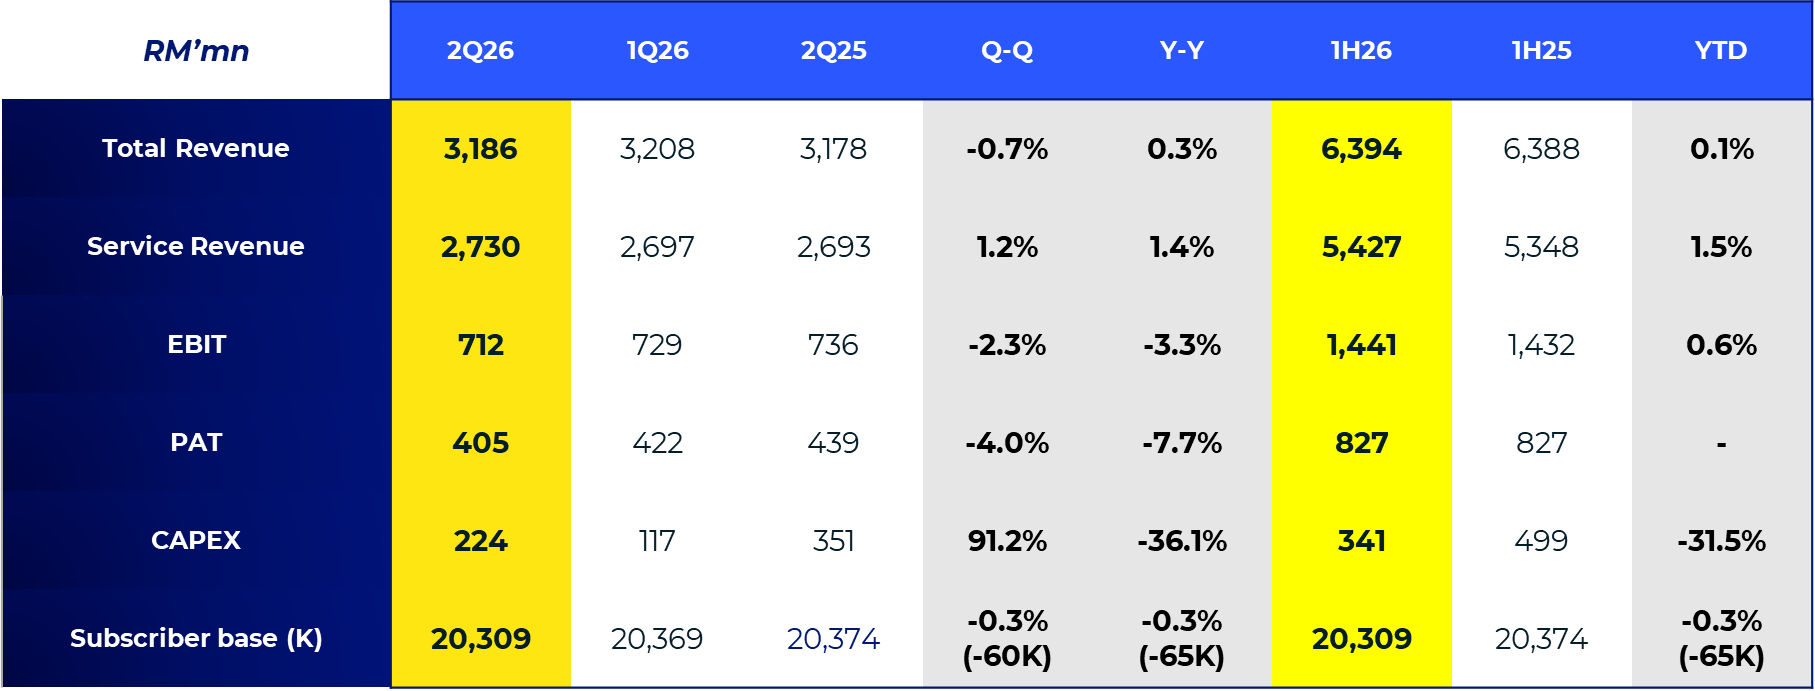
For the first half of FY2026, service revenue grew 1.5% year-on-year (YoY) to RM5,427 million, while Q2 FY2026 service revenue increased 1.4% YoY to RM2,730 million. Earnings before interest and tax for the first half improved 0.6% YoY to RM1,441 million, supported by service revenue growth and lower operating expenses. Profit after tax for the first half was maintained at RM827 million, though it declined 7.7% YoY in Q2 FY2026 due to lower EBIT and higher net finance costs.
The company’s OE program generated RM100 million in savings during the quarter, bringing year-to-date savings to RM141 million, with CelcomDigi stating it remains on track to meet its full-year target of RM470 million. Key contributors included lower leased-line costs, procurement efficiencies, and improvements to infrastructure projects.
The company closed the quarter with 20.3 million subscribers and declared a second interim dividend of 3.4 sen per share. Chief Executive Officer Albern Murty said the quarter’s performance reflects the company’s execution against its priorities of sustainable growth, operational efficiency, and long-term value creation, noting that OE programmes are generating tangible savings while enabling continued investment in the network, digital capabilities, and customer experience.
Prepaid Registration Standards & IT consolidation Progress
CelcomDigi stated it has implemented full operational readiness for the Malaysian Communications and Multimedia Commission’s (MCMC) new prepaid registration mandatory standards, including updates to its digital platforms, retail channels, products, and operational processes.
The company completed its planned network integration and modernization activities for 2026 and is now focused on the final phase of IT consolidation, targeted for completion in the second half of 2027. This phase involves integrating the company’s core billing and CRM systems. CelcomDigi stated it remains on track to deliver steady-state annualized cost savings of approximately RM700 to RM800 million following the completion of integration initiatives post-2027.
Segment Performance Across Postpaid, Home & Fibre, Prepaid, And Enterprise
Postpaid revenue grew to RM1,102 million, up 0.2% quarter-on-quarter and 2.7% year-on-year, with subscribers increasing by 191,000 to reach 6.1 million. ARPU remained stable at RM60. Home and Fibre revenue reached RM95 million, up 7.4% QoQ and 47.2% YoY, driven by demand for CelcomDigi One convergence plans. Subscribers increased by 79,000 to 315,000, while ARPU grew to RM103, up 1.0% QoQ and 8.4% YoY.
Prepaid revenue stood at RM1,016 million, down 0.8% QoQ and 3.2% YoY, with subscribers declining to 11.87 million. ARPU remained stable at RM28, supported by higher-quality acquisitions and increased monthly internet adoption. Enterprise Solutions revenue grew 10.7% QoQ and 19.7% YoY, driven by demand for cybersecurity services and digital solutions, along with new contract wins. Enterprise Mobile revenue on core mobile grew 0.3% QoQ, supported by M2M activations, though it declined 9.9% YoY due to lower Bulk SMS traffic.
Pokdepinion: While CelcomDigi’s operational savings and segment growth point to disciplined cost management, the decline in Q2 profit after tax suggests integration-related expenses and finance costs continue to weigh on near-term profitability.